Is this flat worth buying?
Answer two questions from the listing and see what is left for you after the costs the listing never mentions. No email, no sign-up.
The price in the listing, in any currency.
the purchase currency — the one you negotiate in with the seller
From the same listing, or a similar one nearby.
The base currency: the answer, deposit and bond rates are all in it. Usually the one you keep your money in.
Out of the rent alone, after costs and tax. Selling the flat does not count here: the question is how many years your money is tied up if you never sell.
How long you are willing to wait is yours to set. The full model checks your term, your lead over a bank deposit, and what comes back in a forced sale.
how this is counted
If this line did not exist, the yield would be higher by this much. The first two figures are the ones letting agents know by heart: put in yours and the answer recalculates.
The four lines beside it are counted on your numbers and on typical assumptions; the first two you can adjust right here, the rest in the full model, one question at a time.
So — not worth buying?
Not necessarily. The question is at what price this flat clears your own conditions. The full model works that price out and names it — that is the number you take to the seller.
How it works
The page does not bury you in fields. It asks what an honest adviser would ask — one question at a time — and sharpens the figure with every answer.
Two numbers from the listing
Price and rent. You already see what is promised and what is left after the first three costs.
One question at a time
Tenants, buying costs, upkeep, tax, mortgage. Each one shows “without this it would be X%”, so it is clear why it is worth answering.
An answer on your three conditions
How far it beats a deposit, when the money comes back, what comes back on a forced sale. You set the bars.
What the full model does
Not a spreadsheet — an answer. 180 months, every cost in the month it actually lands.
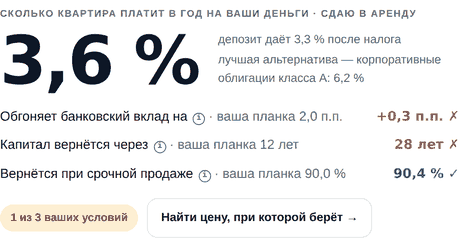
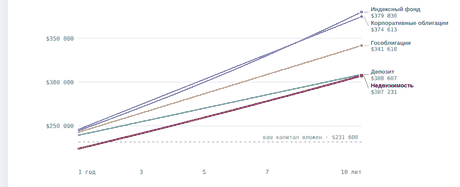
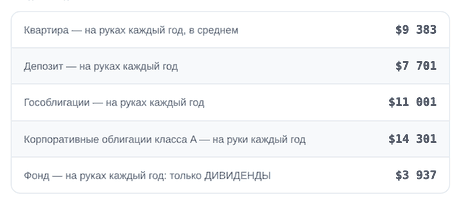
An example at $220,000 and $1,300 a month, on typical assumptions. It is not a sentence on the flat — it is an answer about your bars and these numbers: negotiate, move a bar, or buy it for reasons other than money — but knowing.
This is what it looks like inside
Three screens from the model itself, on the same figures — 220,000 and 1,300 a month. Screenshots, not drawings.
It remembers every flat you check
Not this browser — your account. Sign in anywhere and the list is there.
| Saved as | Conditions met | Its yearly share | The safe option |
Margin over ityou asked 2.00 p.p. | Capital backyou asked 12 years | Back on a forced saleyou asked 90.00% |
|---|---|---|---|---|---|---|
| Lisbon · AlfamaLet out, not sold | 1 of 3 | 3.55%let, then sold 3.27% · never let, sold −2.12% | 3.33% | 0.23 p.p. ✗ | 28 years ✗ | 90.42% ✓ |
| Porto · BoavistaLet out, not sold | 0 of 3 | 1.56%let, then sold 1.27% · never let, sold −1.62% | 3.33% | −1.77 p.p. ✗ | 64 years ✗ | 85.29% ✗ |
What the model returns for two flats at $220,000 and $420,000, both at $1,300 a month, against the same bars of yours.
What it does — and does not do
Every rate is yours to set, so the answer is exactly as good as your numbers. It is an estimate built on your assumptions — not a valuation, not tax advice, and no substitute for an accountant who knows the country. It does not cover everything: no model covers every situation. It does count more of the real costs than most people count before they sign.
The full model, every report, my properties and the comparison.
Open the full modelNot deciding today? Leave your email.
We'll send the checklist “30 costs the listing never mentions” and write when something new lands in the model. Rarely; unsubscribe in any email. The address is used for these emails and nothing else.